Navigating the Kenya Finance Act: Strategic Tax Considerations for Commercial Enterprises
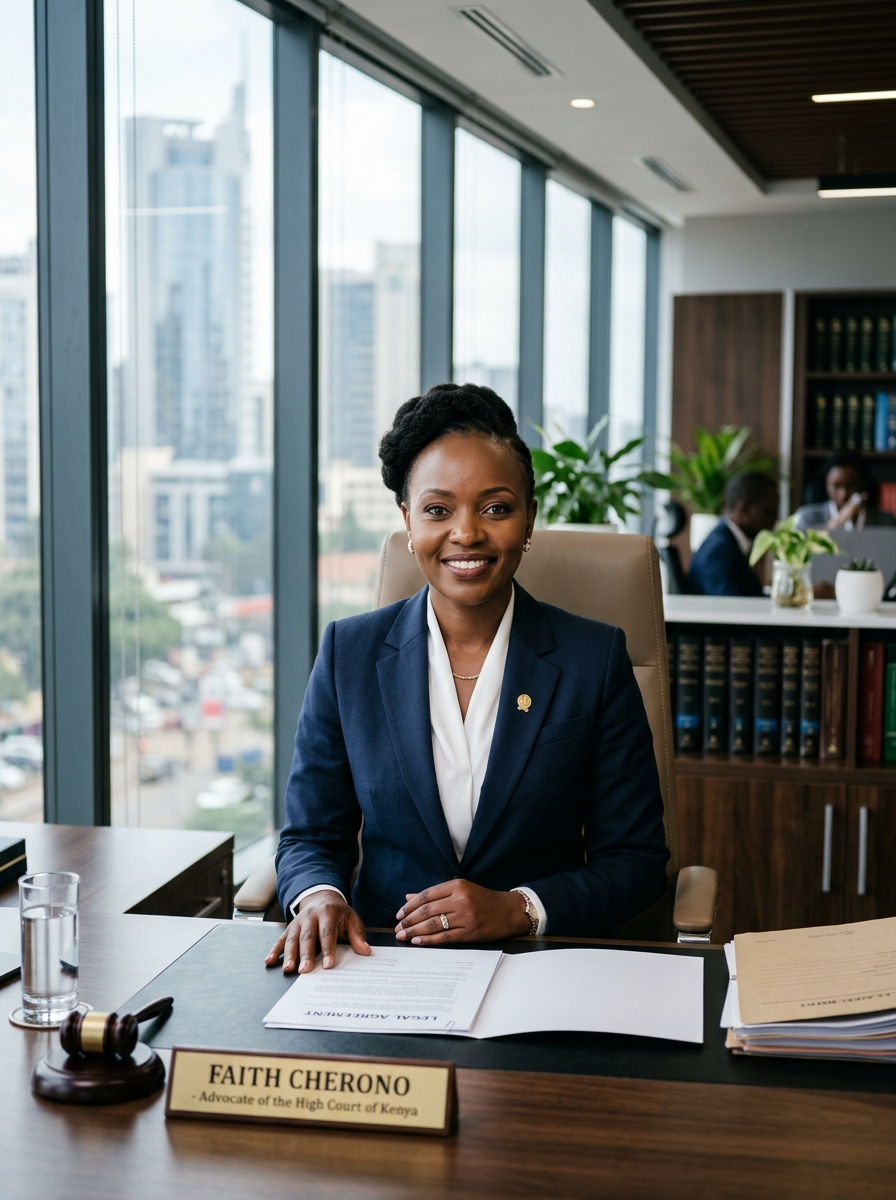
Faith Cherono, Managing Partner
Advocate of the High Court of Kenya • CCA Advocates
The ongoing evolution of Kenya’s fiscal policy via successive Finance Acts has placed compliance at the very top of executive board agendas. Businesses operating in Nairobi and throughout the East African Community now confront an increasingly assertive Kenya Revenue Authority (KRA) equipped with real-time electronic monitoring tools.
In this advisory briefing, we outline key structural changes, risks, and proactive steps corporate leaders should institute to safeguard their operations and balance sheets.
1. Electronic Tax Invoice Management System (eTIMS) Realities
The legal mandate under Section 23A of the Tax Procedures Act requires that any business expense claimed for corporate income tax deduction must be supported by a valid eTIMS invoice. Failure to reconcile contractor and vendor invoices can result in immediate disallowance of operating expenses, resulting in punitive tax liabilities.
2. Mitigating Cross-Border Withholding Tax Disputes
Many multinational firms face aggressive KRA audits regarding payments for digital services, technical fees, and intellectual property royalties paid to parent entities abroad. Ensuring that your Transfer Pricing documentation and Double Taxation Agreement (DTA) filings are aligned is no longer optional.
3. Proactive Engagement with the Tax Appeals Tribunal (TAT)
When informal reconciliations break down, the Tax Appeals Tribunal provides an objective, expedited forum to contest erroneous tax determinations. Strict 30-day statutory notice timelines apply, making rapid legal intervention essential.
Faith Cherono
Founding & Managing Partner • CCA Advocates
Faith advises corporate entities, technology scale-ups, and private investors on corporate governance, M&A, cross-border commercial transactions, and dispute resolution.